The paperwork cleared first. On Monday 13 October, the SEC declared effective the Form S-4 registration statement for Agility Robotics’ proposed merger with Churchill Capital Corp XI — the regulatory green light that puts the Oregon humanoid maker on a documented path to becoming, if shareholders agree, the first publicly listed US pure-play humanoid robotics company. Churchill XI has set the extraordinary general meeting for Sunday 2 November 2026 to approve the combination, with Agility expected to trade on Nasdaq under the ticker AGLT once it closes.
The deal terms, as laid out in the company’s announcement and coverage by Unite.AI and Securities.io: a pre-money valuation of US$2.5 billion, and expected gross proceeds over US$620 million — roughly US$424 million of trust cash assuming no redemptions, plus about US$200 million in a PIPE led by Foxconn. All existing Agility shareholders roll their equity, subject to a 180-day lock-up. The backer list reads like a cross-section of who wants a seat at the physical-AI table: DCVC, NVIDIA, SoftBank Vision Fund 2, Schaeffler, Foxconn, Abico, and Playground Global.
What shareholders are actually being asked to fund
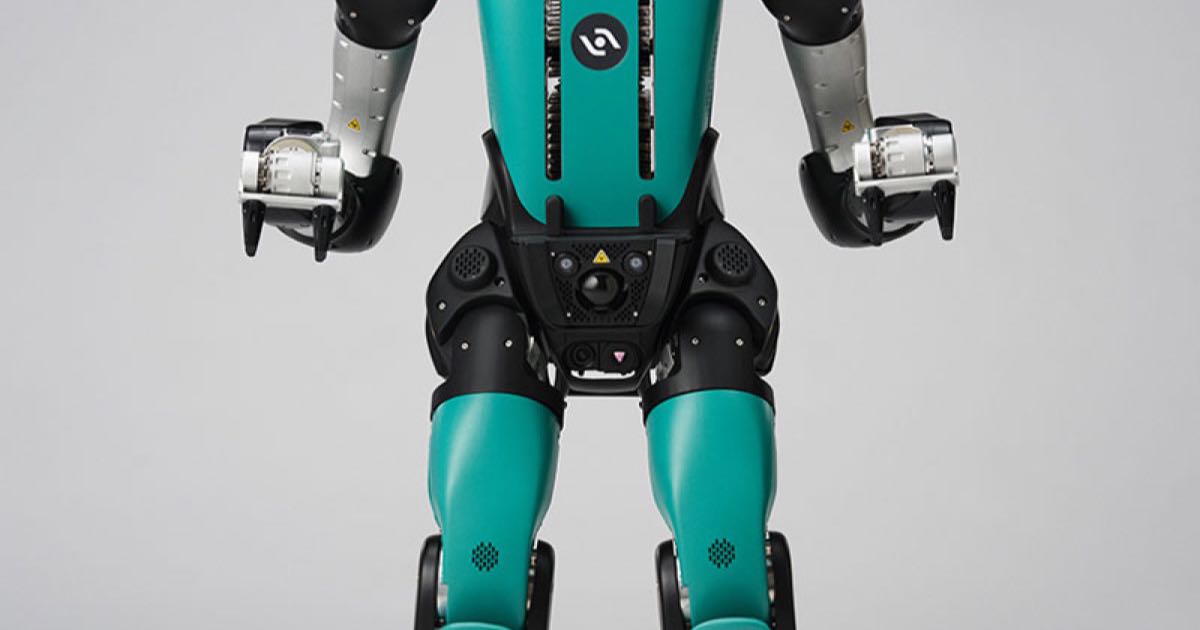
The commercial record is thinner than the milestone language suggests, and the company’s own filings say so. Generations of Digit have logged more than 65,000 hours of real-world operation, and customers include Schaeffler, GXO and Toyota Motor Manufacturing Canada — real deployments, not demo reels. But as our September read of the S-4’s own numbers showed, that history sits on top of US$1.8 million in 2025 revenue against a US$140 million operating loss, and robot leases priced around US$8,500 a month. The fresh capital is earmarked to fulfil orders, expand deployments, scale Digit 5 production, and run RoboFab, the company’s manufacturing facility designed for up to 10,000 robots a year.
That gap between 65,000 operating hours and eight figures of revenue is the deal’s whole story. Investors in the PIPE are betting the deployment curve bends before the cash runs out; the public-market buyers who can first pick up AGLT in November will get to make the same bet with daily liquidity attached.
The listing race now runs through three markets
This is the part with real consequences for how the industry consolidates. Unitree’s Hong Kong listing made China the first market where public investors could buy a pure-play humanoid maker — after Beijing spent 2025 tightening overseas listing rules for exactly this sector. The S-4’s effectiveness means US investors get their instrument a few weeks later, with the 2 November vote the last gate. Europe, for now, has no listed humanoid pure-play at all. Three markets, three ways to price the same question: what is a humanoid robot company worth before its revenue curve proves anything?
For New Zealand readers, the direct exposure is limited — AGLT is not going to be in KiwiSaver default funds this year. But the pricing of these listings sets the cost of capital for every robotics integrator and component supplier downstream, including the ones NZ firms actually contract with. When the market puts a daily price on a US$2.5 billion pre-money humanoid company with US$1.8M of trailing revenue, that number becomes the reference point for every private raise that follows.
The vote is scheduled for 2 November. Assuming shareholders approve and closing conditions are met, AGLT’s first trading day will be the first time anyone anywhere can put a live market price on a US humanoid robot maker — watch it against Unitree’s multiple, not in isolation.
FAQ
📈 What did the SEC actually approve? It declared the Form S-4 registration statement for the Agility Robotics–Churchill Capital Corp XI merger effective on 13 October 2026. That is a registration milestone, not final approval — the deal still requires the 2 November shareholder vote and closing conditions.
🗳 When is the shareholder vote? Sunday 2 November 2026, at Churchill XI’s extraordinary general meeting. If approved, Agility is expected to trade on Nasdaq under ticker AGLT.
💵 How big is the deal? US$2.5 billion pre-money valuation with over US$620 million in expected gross proceeds: about US$424 million of trust cash (assuming no redemptions) and roughly US$200 million from a Foxconn-led PIPE.